Few real estate decisions carry more emotional weight than the choice to upsize or downsize. The family considering a larger home is imagining a version of their life that has not happened yet: more room for children who are growing, space for a home office that actually works, a guest room for parents who visit. The empty nesters considering downsizing are navigating something far more complex: the practical recognition that the family home they raised their children in is now too large for two people, and the grief that sometimes comes with that recognition even when the practical case for moving is clear.
The realtor who understands these emotional layers and knows how to navigate them serves these clients far better than one who simply pulls MLS listings based on the criteria provided.
The Upsizing Conversation: Beyond Square Footage
Buyers upsizing from a smaller home to a larger one are usually managing two transactions simultaneously, and the sequencing of those transactions is one of the most stressful logistical challenges in residential real estate. Most upsizing buyers need to sell their current home to access the equity that funds the down payment on the next one. This creates the classic chicken-and-egg problem: do you sell first and risk not finding the right place to buy before your closing date, or do you buy first and risk carrying two properties simultaneously if your existing home takes longer to sell than expected?
The right sequencing depends on market conditions, the buyer financial strength, and their risk tolerance. In a seller market where homes move quickly and inventory is scarce, buying before selling is more feasible. In a balanced or buyer market where existing home sale timelines are less predictable, selling first and finding temporary accommodation provides more financial certainty. There is no universally correct answer, but there is a right answer for each client situation, and the realtor who thinks through the sequencing problem carefully and presents a clear recommendation with the reasoning behind it is providing genuine strategic value.
Helping Clients Quantify the True Cost of Upsizing
Buyers who are focused on the price difference between their current home and their target home often underestimate the true cost of upsizing. Beyond the sale proceeds and purchase price, they need to account for land transfer tax on the new property, legal fees on both the sale and purchase, moving costs, any immediate renovation or update costs on the new property, and the ongoing carrying cost increase: higher property taxes, higher utility costs for a larger space, and potentially higher maintenance costs.
A realtor who walks an upsizing client through a realistic total cost of the move, including all of these components, provides information that helps the client make a genuinely informed decision rather than one based only on purchase price and mortgage payment. This conversation occasionally results in a client who decides the timing is not right for the upgrade. More often it results in a client who proceeds with clear eyes and feels grateful for the honest preparation.
The Downsizing Conversation: Meeting Clients Where They Are Emotionally
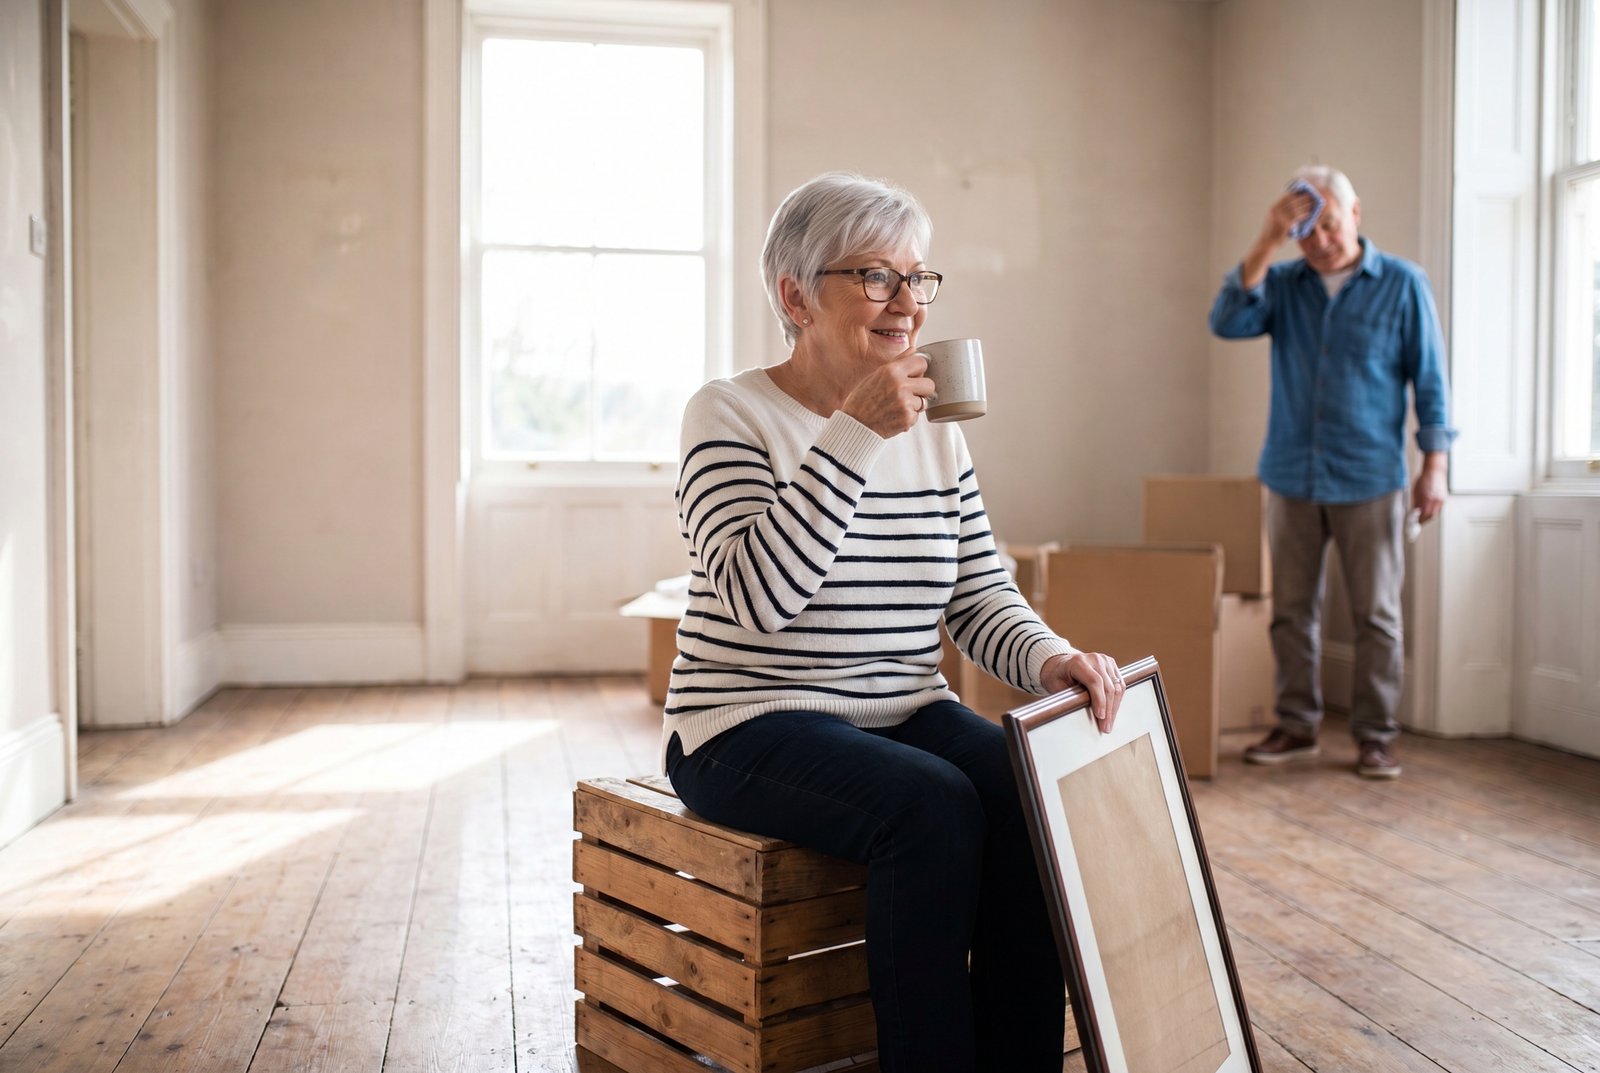
Downsizing clients, particularly those who are selling a family home they have lived in for 20 or 30 years, are often processing a mix of emotions that has nothing to do with real estate in any technical sense. They are saying goodbye to the kitchen where their children learned to cook, the backyard where birthday parties happened, the neighbourhood where they built decades of relationships. The practical case for downsizing may be completely clear to them intellectually while being genuinely difficult emotionally.
The realtor who acknowledges this emotional dimension, who does not rush the client toward decisions before they are ready, and who makes space for the conversations that have nothing to do with square footage or comparable sales, is the one who earns this client trust completely. The practical work of the transaction, the CMA, the listing preparation, the staging, is actually less complex for a straightforward family home than for many other property types. The real work is the human work of accompanying clients through a significant life transition with patience and genuine care.
The Financial Implications of Downsizing That Clients Often Miss
Downsizing clients sometimes assume the equity they release from selling a larger home is straightforward to capture and deploy. In practice, it is more complicated. Land transfer tax applies to the new property purchase. Legal fees apply on both sides. Moving costs for a household that has accumulated decades of belongings can be substantial. The difference in carrying costs, while generally lower on a smaller property, should be modelled rather than assumed. Some downsizers are also surprised to find that a well-maintained condominium in a desirable building in their preferred neighbourhood is less inexpensive than they anticipated.
A clear-eyed financial walkthrough of the downsizing transaction, covering what the net proceeds from the sale look like after costs and what the true cost of the acquisition is, ensures that downsizing clients enter the process with realistic expectations and exit with a result that genuinely improves their financial and lifestyle position.